The Other Driver’s Insurer Is Already Building a Case. Are You?
The Other Driver’s Insurer Is Already Building a Case. Are You?
The call I remember most clearly came from a woman I’ll call Diane. She’d been rear-ended at a red light three days earlier—clear liability, no ambiguity. The other driver had even apologized at the scene. By the time she reached me, she’d already given a recorded statement to the at-fault driver’s insurance company, mentioned that her neck “felt a little stiff but was probably fine,” and agreed to let them handle everything. She was calling because something felt off.
It was. That “probably fine” comment had already been logged. The adjuster had been pleasant, efficient, and completely focused on closing her claim as cheaply as possible. Diane wasn’t suspicious because nothing about the interaction felt adversarial. That’s exactly how it’s designed to work.
I’m not telling you this to frighten you. I’m telling you because Diane did everything a reasonable, polite person would do—and it nearly cost her. You deserve better than that.
What the First Hour Actually Decides
The moments right after a crash feel chaotic, but they’re also when your claim is most vulnerable and most shapeable. What you do—and don’t do—in that first hour creates the foundation everything else is built on.
If anyone is injured, call 911 immediately. Don’t negotiate that decision. A responding officer creates an official record that neither insurer can easily rewrite later. If the crash happens on private property—a parking lot, a gas station—California’s official guidance notes that some police authorities won’t respond to those scenes, which makes your own documentation the only record that exists.
Here’s what to collect before you leave the scene:
- Driver’s license — ask to see it directly, not just a photo someone hands you
- Vehicle registration — verify it matches the driver’s information
- Insurance card — carrier name, policy number, contact information
- License plate — photograph it, don’t just write it down
- Witness names and phone numbers — don’t assume police will collect these
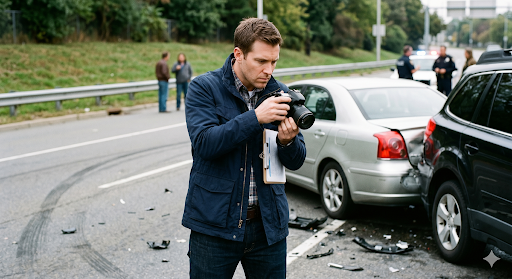
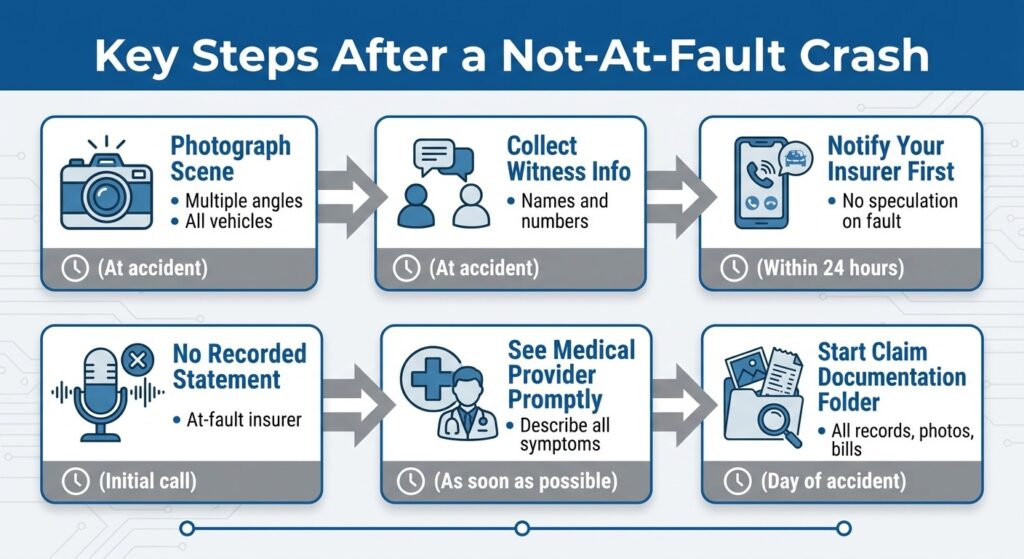
Photograph everything you can safely reach: both vehicles from multiple angles, the point of impact, skid marks, traffic signals, street signs. Do this before anyone moves the cars if possible. Photographic evidence doesn’t argue, doesn’t forget, and doesn’t get nervous under questioning.
Witnesses are worth more than most people realize. A bystander who saw the at-fault driver run a red light can be the difference between a disputed claim and a resolved one.
The 24-Hour Window: Two Calls You Need to Make
Once you’re away from the scene, the clock on several important notifications starts running. The sequence matters.
| Call | Who | What to Say | What to Avoid |
|---|---|---|---|
| First | Your own insurer | Date, location, other driver’s name; confirm you’re reporting as required | Don’t speculate on fault or injuries |
| Second | At-fault driver’s insurer | Confirm the accident occurred; provide basic facts only | Don’t agree to a recorded statement |
Notify your own insurance company first. This feels counterintuitive—why involve your insurer when you didn’t cause the accident? Because your policy likely requires prompt notification of any collision, and because your insurer can sometimes advocate on your behalf or provide coverage options like uninsured motorist protection if the at-fault driver’s coverage falls short. You’re not filing a claim against yourself. You’re activating a resource you’ve been paying for.
When you contact the at-fault driver’s insurance company, keep the initial call factual and brief. The adjuster on the other end is experienced, friendly, and working toward a specific outcome that may not align with yours.
The recorded statement question will almost certainly come up. The at-fault driver’s insurer has no legal right to compel you to give one. Consumer protection guidance is direct on this point: don’t give statements without first seeking advice, because insurers can and do use those statements in the claims process. You can simply say: “I’m not prepared to give a recorded statement at this time. I’ll be in touch once I’ve had a chance to review my situation.” That’s not combative. That’s reasonable.
Building Your Documentation System
This is where a lot of injured parties lose ground without realizing it—not through one dramatic mistake, but through scattered, incomplete records that leave gaps the other insurer is happy to fill with their own interpretation.
Start a dedicated folder the day of the accident. Everything goes in it.
What belongs in your claim folder:
- Police report number and instructions for obtaining the full report
- All scene photographs, timestamped
- The other driver’s complete information
- Witness names and contact details
- Your own written account of what happened (written while memory is fresh)
- Every communication with any insurance company, summarized in writing after each call
The police report deserves specific attention. Once it’s available, obtain a copy and read it carefully. Officers sometimes record details incorrectly—wrong vehicle descriptions, transposed names, or a narrative that doesn’t match what witnesses saw. If there’s an error, you can typically request a correction or submit a supplemental statement. An uncorrected error in an official report can create friction in your claim that takes real effort to undo.
If the other driver was cited, that citation matters. If they weren’t, your photographic evidence and witness accounts become even more important.
Medical Documentation: The Part People Underestimate Most
Adrenaline is real.
After a crash, many people genuinely don’t feel hurt—or feel only mildly uncomfortable—and decide to wait and see. A week later, the neck stiffness that seemed minor has become something that disrupts sleep and limits movement. But now there’s a gap in the medical record, and the insurance company will point to that gap as evidence the injury wasn’t serious or wasn’t caused by the crash. This is one of the most predictable and preventable ways strong claims get undermined.
See a medical provider as soon as possible, even if you feel okay. Tell them you were in a motor vehicle accident. Describe every symptom, even the ones that seem minor—headache, stiffness, soreness, difficulty concentrating. Let the provider document what you’re experiencing. That documentation creates a contemporaneous medical record tied to the date of the crash, which is far harder to dismiss than a visit two weeks later.
What to track and keep:
- Every medical bill, even small copays
- All treatment records and discharge summaries
- Prescription receipts
- Documentation of missed work days and lost wages
- Out-of-pocket expenses related to the injury (transportation to appointments, home care, etc.)
The full picture of your damages is what an insurance claim is ultimately measured against. You need that picture to be complete and organized before you negotiate anything.
If your injuries are significant, or if the insurance company starts pushing back on your claim, this is the moment to consider consulting a personal injury attorney boston or wherever you’re located. Not because you’re being aggressive—because an attorney who handles these cases regularly knows what your claim is actually worth, knows how to respond to lowball offers, and can prevent you from settling for less than you need before you know the full extent of your recovery. Most work on contingency, meaning no upfront cost.
When the Other Insurer Pushes Back
So you’ve done everything right, and the at-fault driver’s insurance company is still making things difficult. Maybe they’re disputing liability. Maybe they’re offering a settlement that doesn’t come close to covering your medical bills. Maybe they’ve gone quiet.
Understand this clearly: the adjuster’s job is to resolve claims efficiently for their employer. They are not your advocate. They may be polite, even sympathetic, but their professional incentive is to close your claim at the lowest defensible number. That’s not cynicism; it’s just how the business works.
Three things to do when pushback starts:
- Put everything in writing. If they’re disputing fault despite a police report and photographic evidence, that dispute needs to be addressed in writing. Follow up every phone call with an email summarizing what was discussed. Create a paper trail that shows what was said and when.
- Don’t accept a settlement before treatment ends. If a settlement offer comes in before you’ve completed medical treatment, be very cautious. Once you sign a release, that’s typically final—you can’t go back for additional compensation if your injury turns out to be more serious than initially thought.
- Get a professional evaluation of any offer. Before you respond to a number, understand what that number actually covers relative to your documented damages and anticipated recovery.
The Concerns I Hear Most Often
“I wasn’t at fault—why do I have to do all this?”
Because fault and compensation aren’t the same thing. Being not at fault means the other driver’s insurer is financially responsible. It doesn’t mean they’ll pay fairly without documentation to support your claim. The evidence you gather is what turns legal responsibility into actual compensation.
“Won’t getting a lawyer make me seem difficult?”
No. It makes you seem like someone who understands the process. Insurance companies deal with attorneys every day. What they’re counting on is that you won’t consult one—that you’ll accept the first offer because you don’t know what your claim is worth.
“I feel fine right now. Do I really need to see a doctor?”
Yes. Symptoms from whiplash, soft tissue injuries, and even mild concussions can take days to fully surface. A medical visit now creates the record that protects you later. Skipping it is one of the most common and costly mistakes in otherwise solid claims.
Your Next Concrete Steps
If you’re reading this right after a crash:
Photograph the scene. Get witness contacts. Request the police report. See a medical provider today. Notify your own insurer. Do not give a recorded statement to the at-fault driver’s insurer without guidance.
If you’re a few days out and already feeling the pressure:
Pull together everything you have. Get to a doctor if you haven’t already. Consider a free consultation with a personal injury attorney before you respond to any settlement offer. Post-crash guidance consistently reinforces this sequence—and for good reason. The steps build on each other, and skipping one creates gaps the other side will use.
You’re not being paranoid. You’re not overreacting. You’re doing what anyone should do when they’ve been injured and someone else is responsible—making sure your voice is part of the record before the other side finishes writing it.